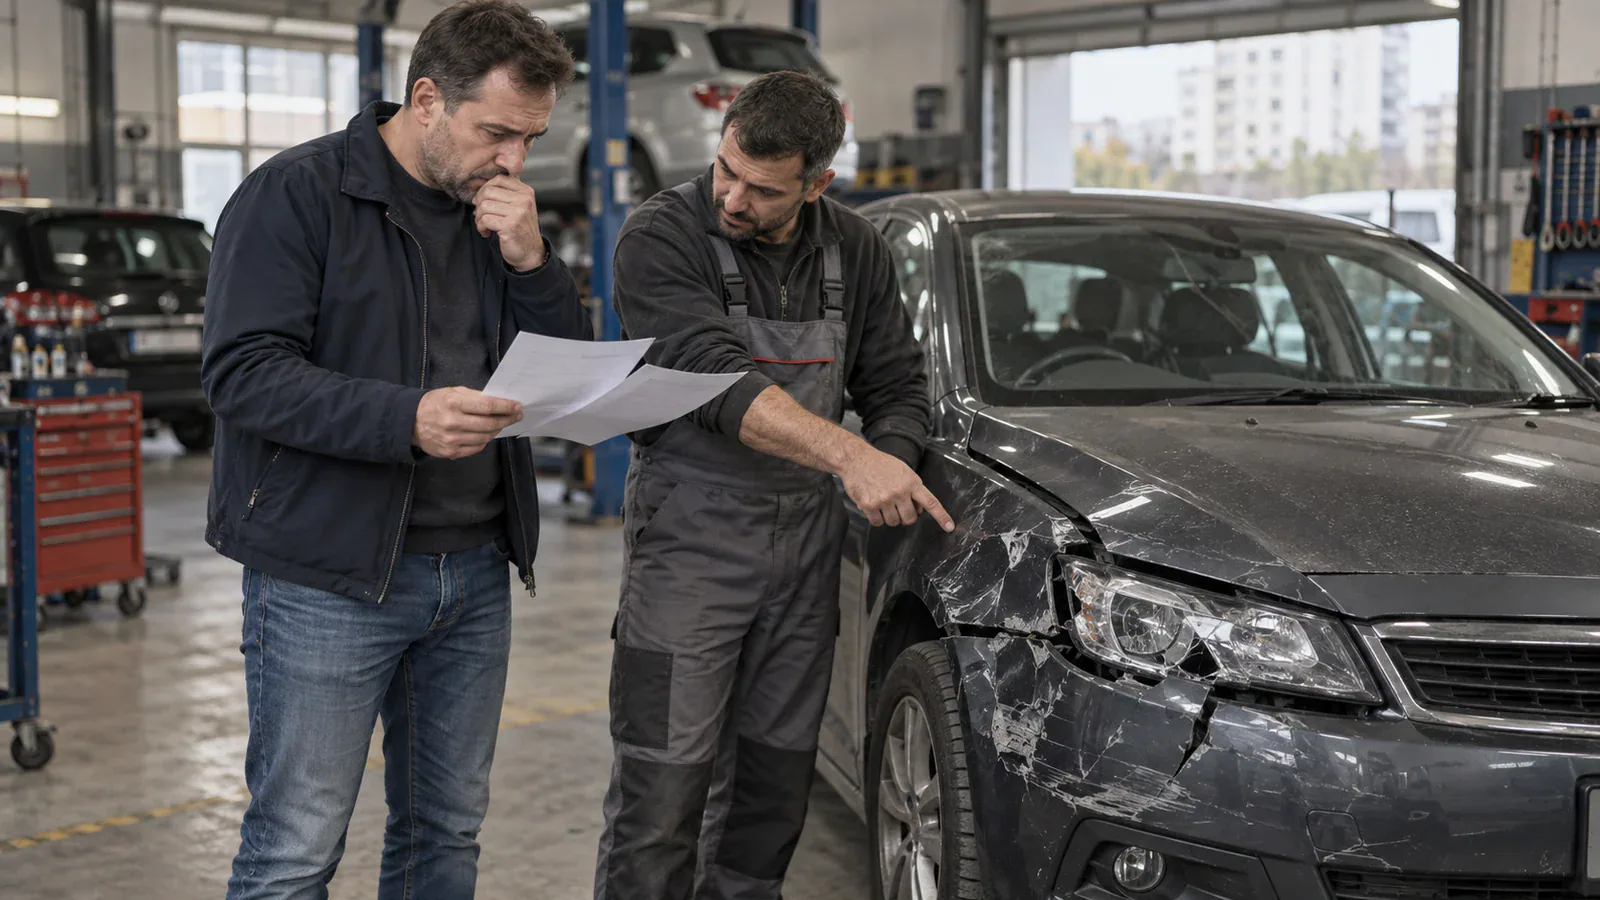
Imagine: the accident is over, your car is at the repair shop, and the insurer asks you to wait. Or offers too little to restore it. You need repairs now. Who will cover the difference, and how much longer will you wait?
A crash can cost you money twice
The first loss is immediately visible: a damaged bumper, headlight or bodywork. The second can emerge later, when you need repairs now but the insurance payment has not arrived or the offer is insufficient.
To protect your position:
- document the damage before repairs and keep the paperwork;
- check the dates of your claim and the insurer's decision, rather than relying on telephone promises;
- request a detailed calculation if the payout seems questionable;
- do not sign a final settlement agreement before understanding its consequences.
This article concerns damage to an injured party's vehicle under domestic RCA insurance in Moldova. RCA is compulsory motor third-party liability insurance. It does not replace CASCO comprehensive insurance or mean that an at-fault driver's own RCA policy will pay to repair their vehicle.
Payment delays are a documented problem
In May 2026, CNPF reported on its examination of more than 22,000 RCA claim files at nine insurers. In 5,072 files — 23% of the sample — payment exceeded the 10-working-day deadline following the insurer's decision. The review covered January–September 2025.
This does not mean that one in four claimants received no payment at all. CNPF also noted that, in some cases, claimants' late submission of payment details contributed to delays. Nevertheless, failures to meet deadlines are officially documented. CNPF review findings.
For a vehicle owner, waiting can mean additional spending on taxis, parking or repairs funded from the family budget. Whether particular additional expenses can be recovered depends on the circumstances and supporting evidence.
“Your claim is being processed” does not repair your car.
“Please wait” is not a deadline: check the dates
RCA claims have specific deadlines. CNPF's guidance and decision set out the following:
- Up to 5 working days after receiving the claim to inspect damaged property and draw up a damage assessment report.
- Up to 30 days after the claim is filed for the decision and payment where the claim file is complete.
- Up to 90 days after the claim is filed where the file is incomplete.
- Up to 10 working days after the decision to pay compensation.
The 30- and 90-day periods are expressed in days, not working days. The 10 working days following a decision must not simply be added to the overall deadline as permission to delay payment. These obligations must be considered together. CNPF Decision No. 24/2 of 18 May 2026, applying Articles 20 and 29 of Law No. 106/2022.
Ask in writing when your claim was registered, which documents are missing and when the decision was issued. Supply accurate bank details and retain proof of submission.
If you hear “the file is incomplete”, ask a specific question: what is missing, and why is it necessary for my claim?
Is your insurer delaying or offering too little?
Contact Colenco Legal to review the decision, calculation and correspondence. We can assess grounds for a challenge and the evidence needed.
Three mistakes that weaken your position
Repairing the car without preserving evidence. Once damaged parts have been discarded and the vehicle reassembled, proving the original damage may become harder. Before repairs, document the damage through photographs, the inspection report and repair shop records. If dismantling reveals hidden damage, notify the insurer in writing and arrange for it to be documented. This is a practical way to protect evidence, not an absolute prohibition on repairing a vehicle.
Signing documents just to receive payment sooner. Wording such as “no further claims” or “full and final settlement” needs checking before you sign. Its legal effect depends on the entire document. Receiving money and signing a separate agreement ending a dispute are different actions.
Keeping all communication on the phone. A call can clarify the status of your file. A written request with proof of receipt helps establish what you requested and when. Keep correspondence, attachments and replies together.
The payout will not cover repairs: challenge the calculation
Suppose a repair shop quotes MDL 60,000, while the insurer offers MDL 35,000. This is a hypothetical example. The MDL 25,000 difference does not itself prove unlawful underpayment: both calculations need to be examined.
Compare the insurer's calculation, inspection report and repair estimate:
- do they list the same damage;
- which parts are to be repaired and which replaced;
- are necessary work and materials included;
- how are differences in prices explained;
- which items have been excluded, and why?
The repair estimate supports your position, but does not automatically oblige the insurer to pay any amount listed. A technical disagreement may require an independent assessment.
Do not delay written objections. CNPF specifies 5 days after completion of the claim file for objections to the compensation amount. The insurer must address them within 5 working days of notification. If the completion date is unclear, immediately request that date and a copy of the decision.
If you disagree with the amount, the insurer must still pay the sum it has determined, and you may challenge its decision in court. The five-day objection period should not be treated as automatically extinguishing every right to legal protection once it expires. CNPF guidance on RCA compensation.
If the issue remains unresolved, make a written complaint
Your complaint should contain verifiable facts and a specific request:
- The claim number, accident date and date of your compensation claim.
- What you dispute: a missed deadline, refusal or particular calculation items.
- Supporting evidence: the decision, inspection report, repair estimate and correspondence.
- Your request: payment of the approved amount, an explanation of the calculation or reconsideration of specified items.
Keep proof of delivery or registration. The general deadline for a financial service provider to answer a complaint is 15 working days, unless a special statutory deadline applies. The specific deadline discussed above for objections to an RCA compensation amount is 5 working days.
If the reply does not resolve the issue, or no reply arrives within the applicable period, you can petition CNPF, Moldova's National Commission for Financial Markets. Attach proof of your initial complaint and any reply received. A petition sent directly to CNPF without first complaining to the insurer will be forwarded to the insurer. CNPF complaints procedure.
Court proceedings are also possible under the applicable procedure. Contacting the regulator is not a guarantee that the disputed amount will be recovered.
When legal assistance is useful
A legal review is particularly useful if the insurer has refused payment, a deadline has passed, the calculation differs substantially from the repair documents, or you are asked to sign an agreement waiving further claims.
For an initial assessment, prepare the insurer's decision, compensation calculation, inspection report, repair estimate and correspondence. These documents help assess the grounds for a dispute, missing evidence and whether further costs are justified.
The accident has already caused you a loss. Before agreeing to cover a disputed shortfall yourself, check how it was calculated.